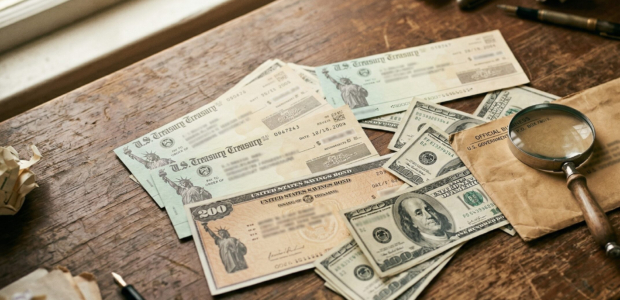

Somewhere in a dresser drawer, a safe-deposit box or a shoebox full of your parents’ papers, there may be a savings bond that stopped paying interest years ago.
You’re not alone. In 2023, the Department of the Treasury’s Bureau of the Fiscal Service said Americans were sitting on nearly $40 billion in savings bonds that have stopped paying interest and ought to be cashed in.
Back in 2019, the figure was more than $26 billion. That’s up roughly $14 billion in less than four years.
That’s money sitting idle while inflation chips away at it. And the tool most people used to hunt for forgotten bonds is gone: Treasury Hunt went dark on Sept. 30, 2025.
I’ve been a CPA since 1981, and I’ve been writing about money for more than 35 years. Here’s how to tell whether your bonds are dead money, how to find the ones you’ve lost track of, how to cash them — and the tax catch a lot of people miss.
1. Know which bonds have stopped earning
Savings bonds don’t send you a letter when they quit paying. They just stop.
According to the Treasury, every bond from Series A, B, C, D, E, F, G, H, J and K, along with old Savings Notes, no longer earns interest.
Today, only I bonds, plus some EE bonds, still pay. EE and I bonds stop earning 30 years after they’re issued. HH bonds stopped at 20.
So do the math on whatever you’re holding. An EE bond issued in 1995 hit 30 years in 2025. It’s done growing. Holding it any longer earns you exactly nothing.
2. Search your state, because Treasury Hunt is gone
If you think a bond exists but can’t find the paper, the old advice was to search Treasury Hunt. That tool is no longer available. The Treasury says the change came under the SECURE 2.0 Act, and questions about unclaimed Treasury securities now go through each state’s unclaimed property program.
The Treasury points people to unclaimed.org, run by the National Association of Unclaimed Property Administrators, to find the right state office. The same group runs MissingMoney.com, a free site that searches participating states’ databases at once.
Start with the state where the original buyer lived when the bond was purchased. Have this ready:
Your full legal name or the name of the original purchaser
Where the buyer lived at the time of purchase or their last known address
Paperwork that proves who you are and, if you’re an heir, your relationship to the owner, such as a death certificate
While you’re searching, look for other money with your name on it. Texas alone has returned more than $5 billion.
3. Cash the paper bonds you already have
If the bonds are in your hand, you have two ways to turn them into money.
The first is your bank. According to the Treasury, you can cash bonds at a bank where you have an account, but each bank sets its own cap on how much it’ll cash in one visit, and some won’t touch savings bonds at all. Call ahead.
The second is the Treasury itself. You can mail the bonds along with FS Form 1522, and the Treasury says it doesn’t cap how many bonds you send or what they’re worth.
If the bonds are worth more than $1,000, you’ll need your signature certified, typically at a bank.
Once that money’s back in your hands, don’t let it go back to sleep in a checking account that pays nothing. You can compare rates on high-yield savings accounts and CDs in our Solutions Center.
Quick gut-check — if your money advice is coming from random online influencers, you’re playing a dangerous game. I’ve been a CPA since 1981 and writing about money since before the internet existed. Sign up for the free Money Talks Newsletter and get expert advice that’s been tested by time.
4. Replace bonds that are lost, stolen or destroyed
A missing piece of paper doesn’t have to mean the money’s gone. You can ask the Treasury to replace bonds that were lost, stolen or destroyed, or to pay you for them, using FS Form 1048.
You’ll need to sign that form in front of a notary or a certifying individual, so don’t sign it at the kitchen table and mail it off.
5. If the owner has died, here’s what heirs need
This is where a lot of bonds get stranded. Mom kept them in a drawer, nobody knew, and the paper sat there for decades after they stopped paying.
If the estate isn’t going through formal probate, the Treasury’s FS Form 5336 lets a family member claim the bonds as a voluntary representative.
The form follows what the Treasury calls an order of precedence, a pecking order for who can act, and you’ll sign it in front of a certifying individual.
If you’re searching through a state office, the Treasury says to have documents like a death certificate and proof of your relationship ready, so gather those first.
If you’re settling a loved one’s affairs, bonds aren’t the only thing that slips through the cracks. Life insurance is another big one. Here’s a CPA’s guide to where a late spouse’s money often hides.
6. The tax catch: The bill may already be overdue
Here’s the part that surprises people.
Many savings bond owners don’t report the interest year by year, and that’s legal. The IRS lets you postpone reporting it until the year you cash the bond or the year it matures, whichever comes first.
Read that again. Whichever comes first. If your bond reached final maturity in 2015 and you never cashed it, the IRS expected that interest to be reported for 2015 — not whenever you finally get around to the bank.
The good news is that savings bond interest is exempt from state and local income taxes, according to the IRS. It’s only Uncle Sam who wants a cut.
When you cash a bond, expect a Form 1099-INT. If a bank cashed it, the bank sends the form, sometimes on the spot. If the Treasury cashed it, the form arrives the following January.
If you’re cashing a bond that matured years ago and you’re not sure the interest was ever reported, talk to a tax professional before you file.
The bottom line
A bond that’s stopped earning isn’t a savings account. It’s a piece of paper that’s losing value every year to inflation.
Spend an afternoon on this. Check the series and issue dates on any bonds you hold. Search your state’s unclaimed property records, and the records of any state where your parents lived. Then cash what’s dead and put the money somewhere it can grow again.
If you’ve already tracked down the bonds, check one more place: old jobs. Here’s the free tool that can help you find a lost 401(k) or pension.